SBI
VFC Rise maps working capital, GST overdraft and loan against property to partner banks and NBFCs. Sanction stays with the lender.
Private company
MSME finance desk, not a personal-loan wall
Udyam-first
Files built around the enterprise
Bank / NBFC sanction
We map the file. Lenders decide.
India
Factories, traders, shops and professionals
Services
Stock, a machine, a shop, or a clean term loan — pick the use, not a generic EMI. Each card opens that facility’s own page.
Working capital
GST-return based overdraft for MSMEs whose sales show clearly on GSTN and match the current account — one of India’s most requested working-capital products.
Open page →
Working capital
Short-term and revolving funds so stock, payroll, GST and suppliers do not wait on collections.
Open page →
Collateral-light
MSME term credit without mortgaging property — underwriting rests on GST, ITR, banking and bureau, not on a ‘no documents’ slogan.
Open page →
Term & expansion
Finance plant, tools and equipment so capex does not drain MSME working capital.
Open page →
Property-backed
Higher-ticket MSME funding using residential or commercial property as security.
Open page →
Collateral-light
Guarantee-backed, collateral-light credit for eligible micro and small enterprises.
Open page →
Sectors
A factory file is machinery and power load. A trader file is GST and crates. Open a sector for photos and the usual product mix.
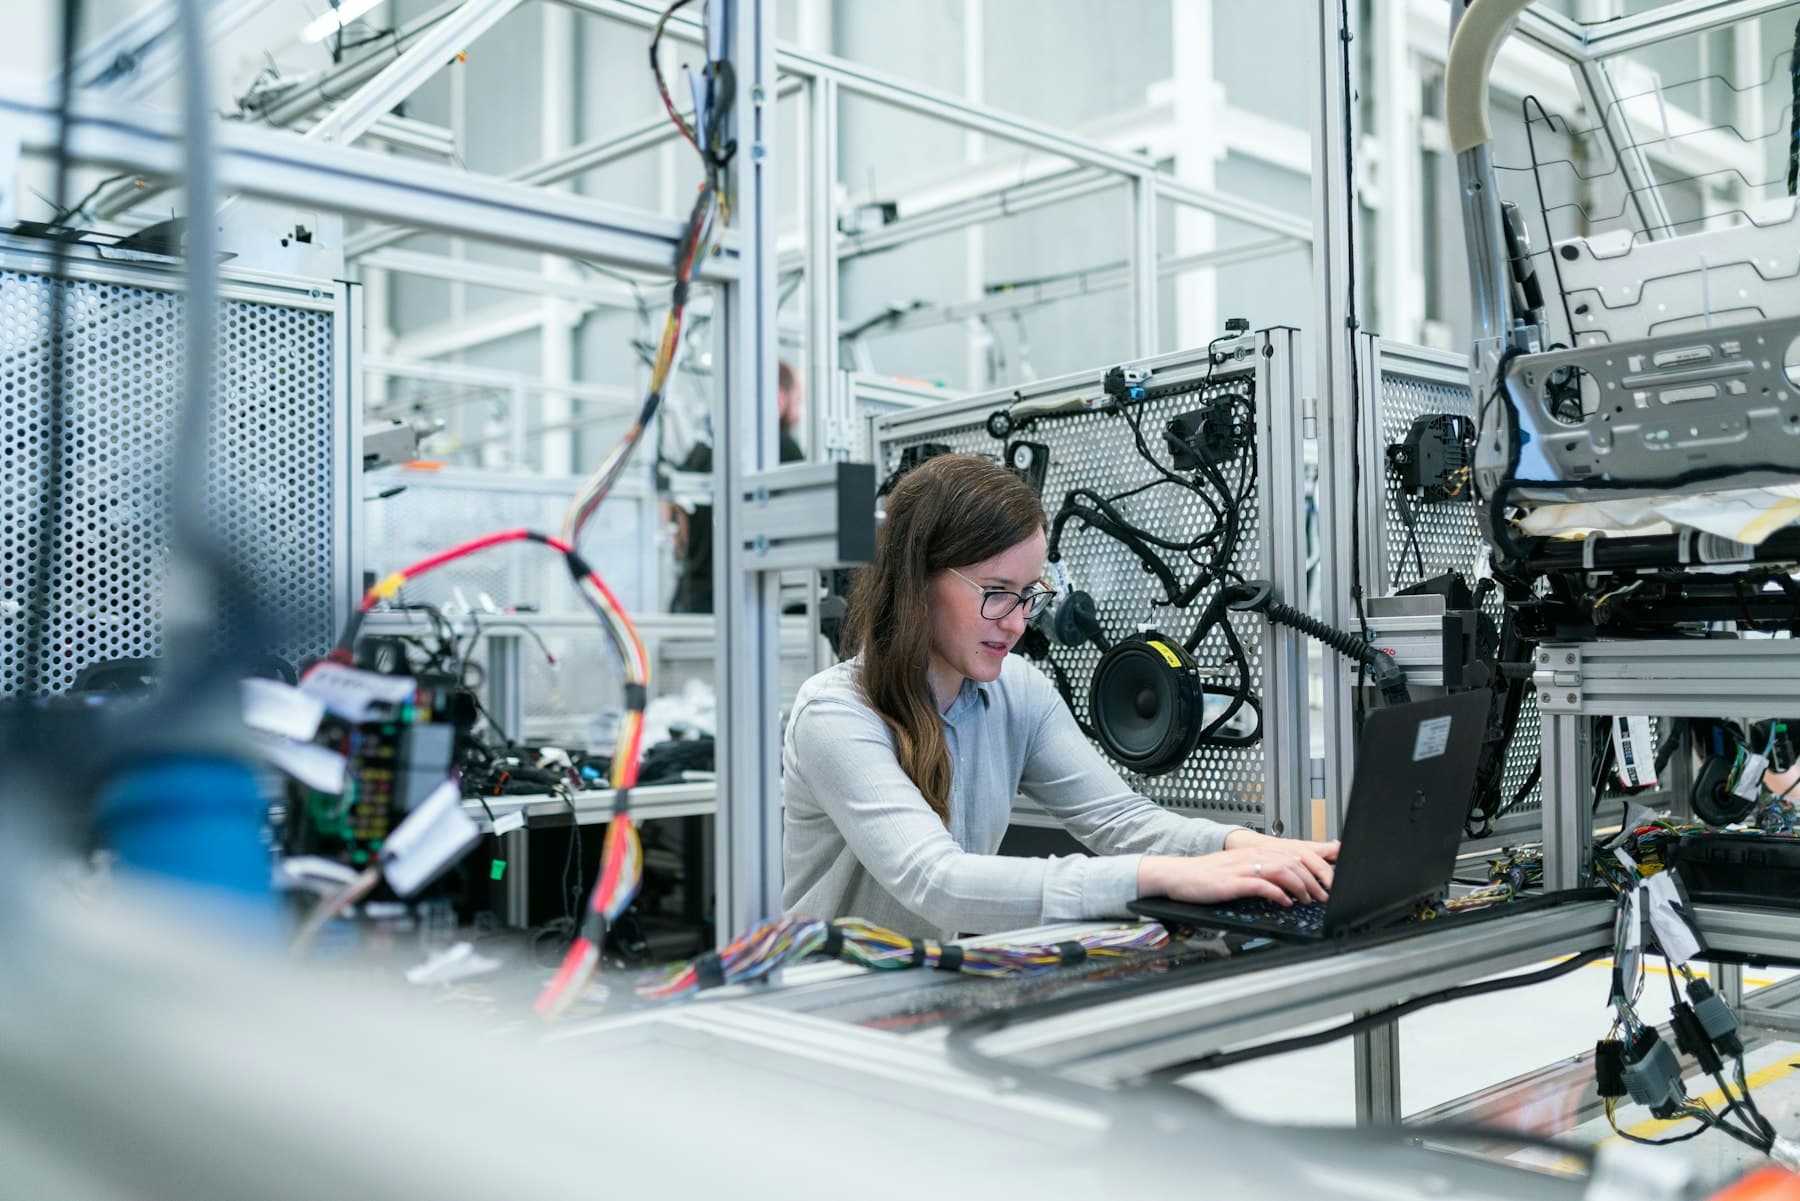
Machinery loan · Working capital / CC · Project expansion · LAP
Open page →
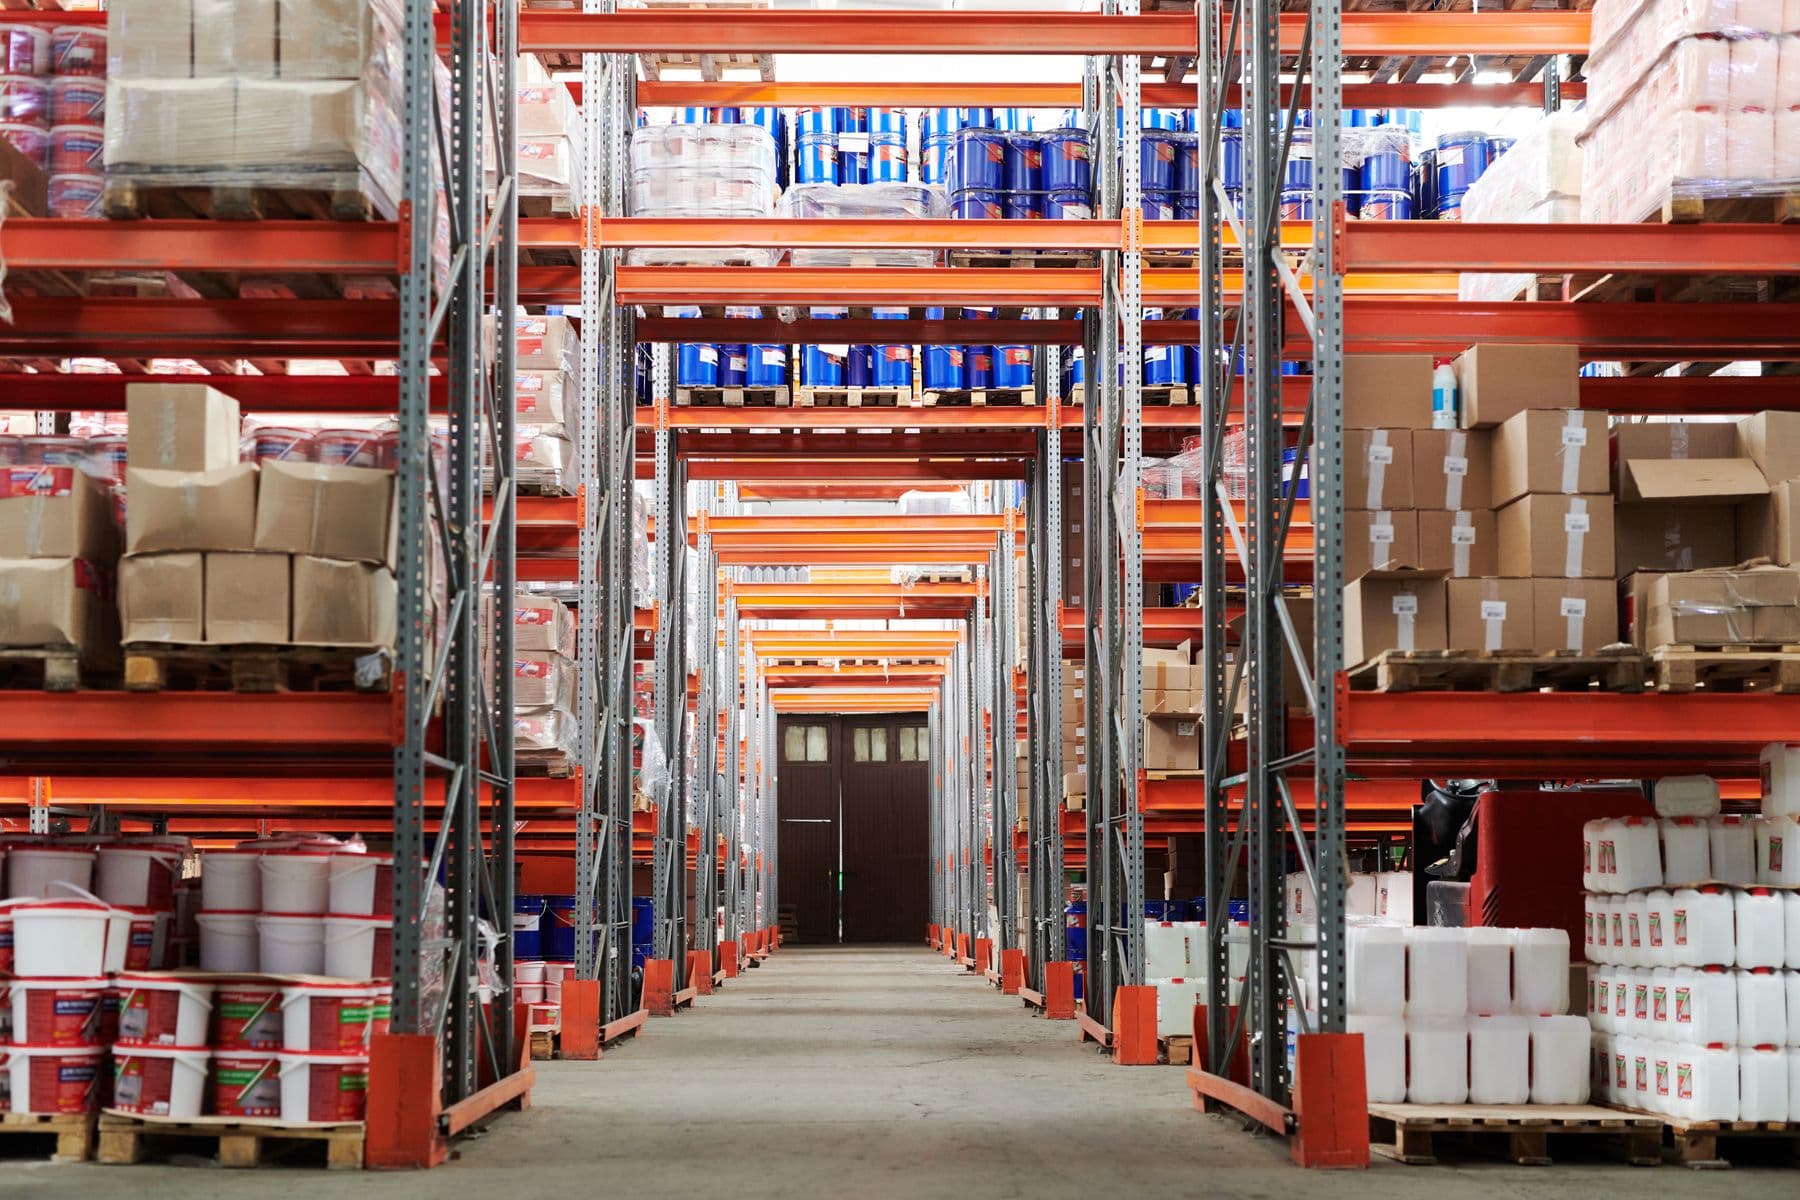
Cash credit · Working capital · Invoice discounting · Shop loan
Open page →
Business OD · Equipment · Term loan · LAP
Open page →
Working capital · Shop loan · LAP · Top-up
Open page →
Schemes
Scheme names are not a shortcut around GST and banking. Each card opens that facility’s own page.
Partners
An MSME file goes to the lender that fits GST, banking and security — not a poster rate. Sanction, if it happens, is in their name.
SBI
ICICI Bank
HDFC Bank
Axis Bank

Bank of India
PNB
Canara Bank
Bank of Baroda
Listing a lender does not mean every file is logged there, or that a rate is promised. Credit policy stays with the bank / NBFC / HFC.
Documents
Original Aadhaar does not belong on a website form. Open a paper for why credit asks it — with photos.
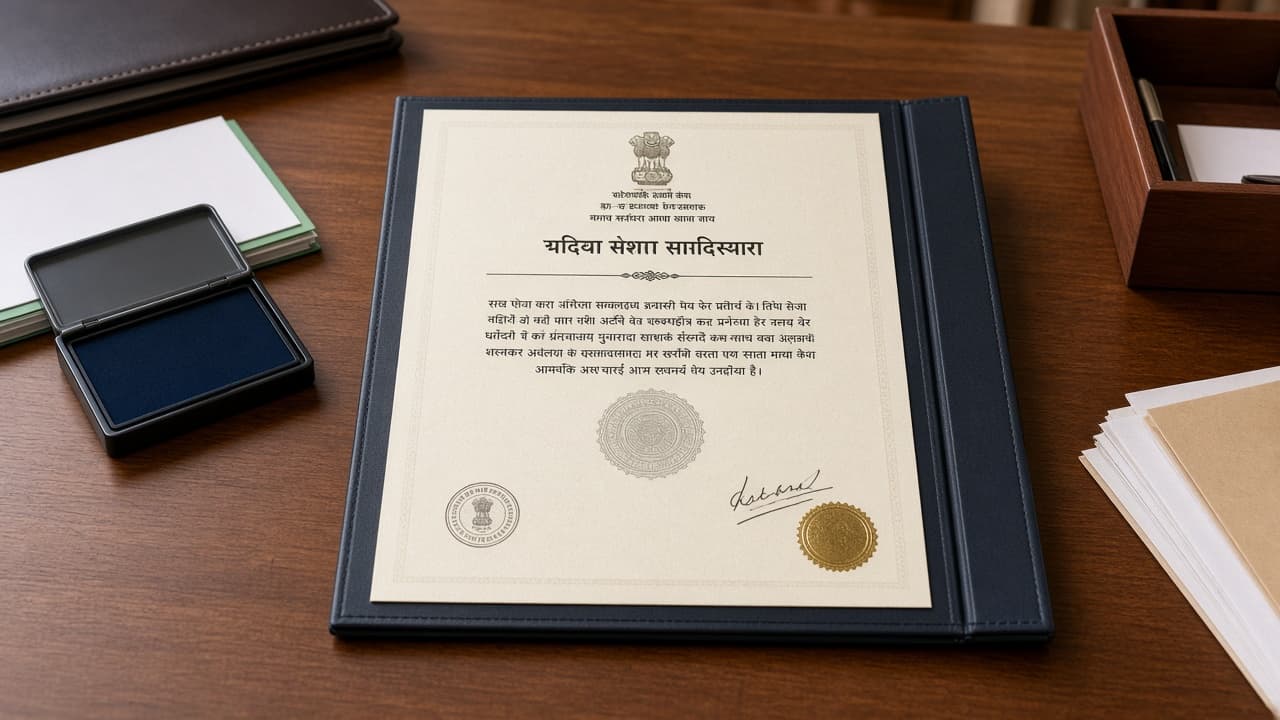
The MSME identity on the file. Update it if constitution changed.
Open page →
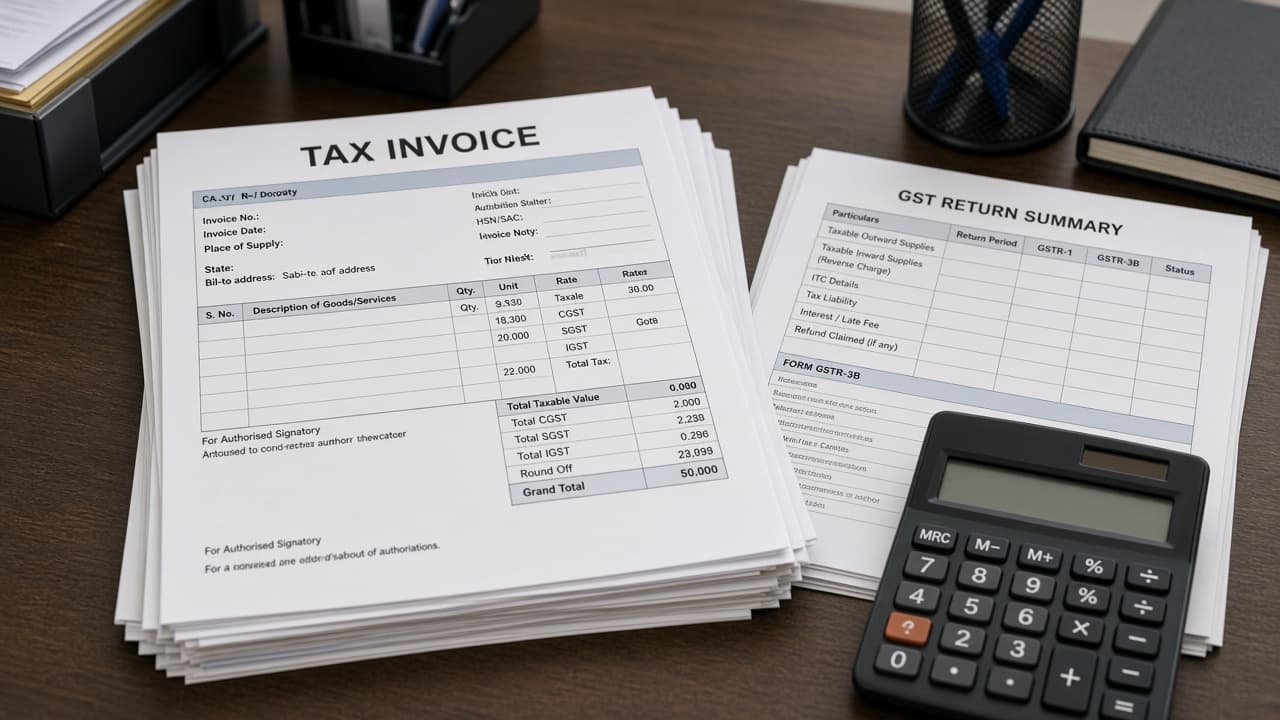
GSTR should be reconcilable with banking. Credit will ask.
Open page →
Official PDFs, 6–12 months, including every account that runs sales.
Open page →
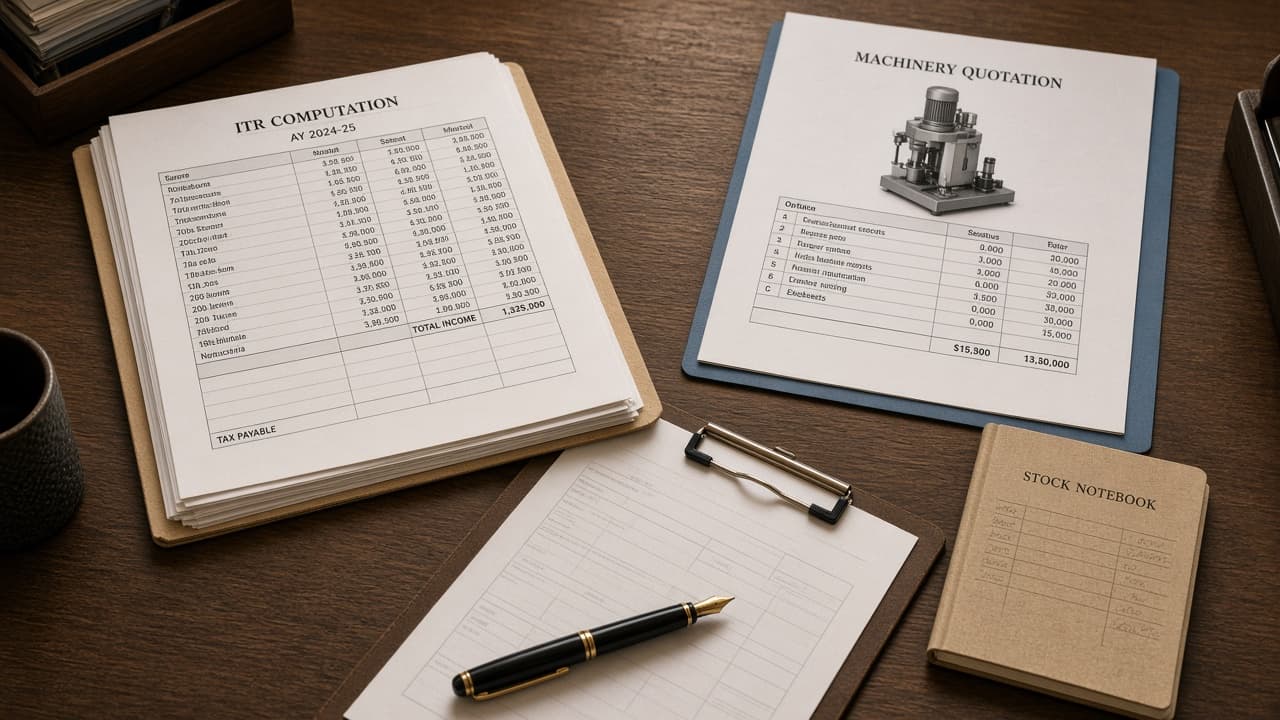
Stock is not a machine, a machine is not a house. One story per facility.
Open page →
Process
Kirana, factory, trader or clinic — same desk path. Stock is not a machine. A shed is not cash credit. Udyam labels the unit; GST and banking still have to talk to each other.
Working capital cycle
GST OD, CC, WC — stock, debtors, GSTR vs the current account.
Term & plant
Machinery, CV, project — vendor quotation and margin, often paid to the dealer.
Property & schemes
LAP or shop against title. CGTMSE / PMEGP / Stand-Up India only if that grid fits.
Step 01
Share basic business details and what you need the funds for — stock, expansion, machinery or property-backed finance.
Step 02
We help identify suitable financing options based on Udyam, GST, banking and end-use — not a guaranteed yes.
Step 03
Explore available options from our lending network of banks, NBFCs and HFCs that fit your file.
Step 04
Our team assists you through documents and the application process with clear communication.
Step 05
Complete the lender’s process. Sanction, rate and disbursal — if approved — stay with the bank or NBFC.
Real MSME desks, real end-use — illustrative outcomes from files we mapped. Sanction always rests with the bank or NBFC.
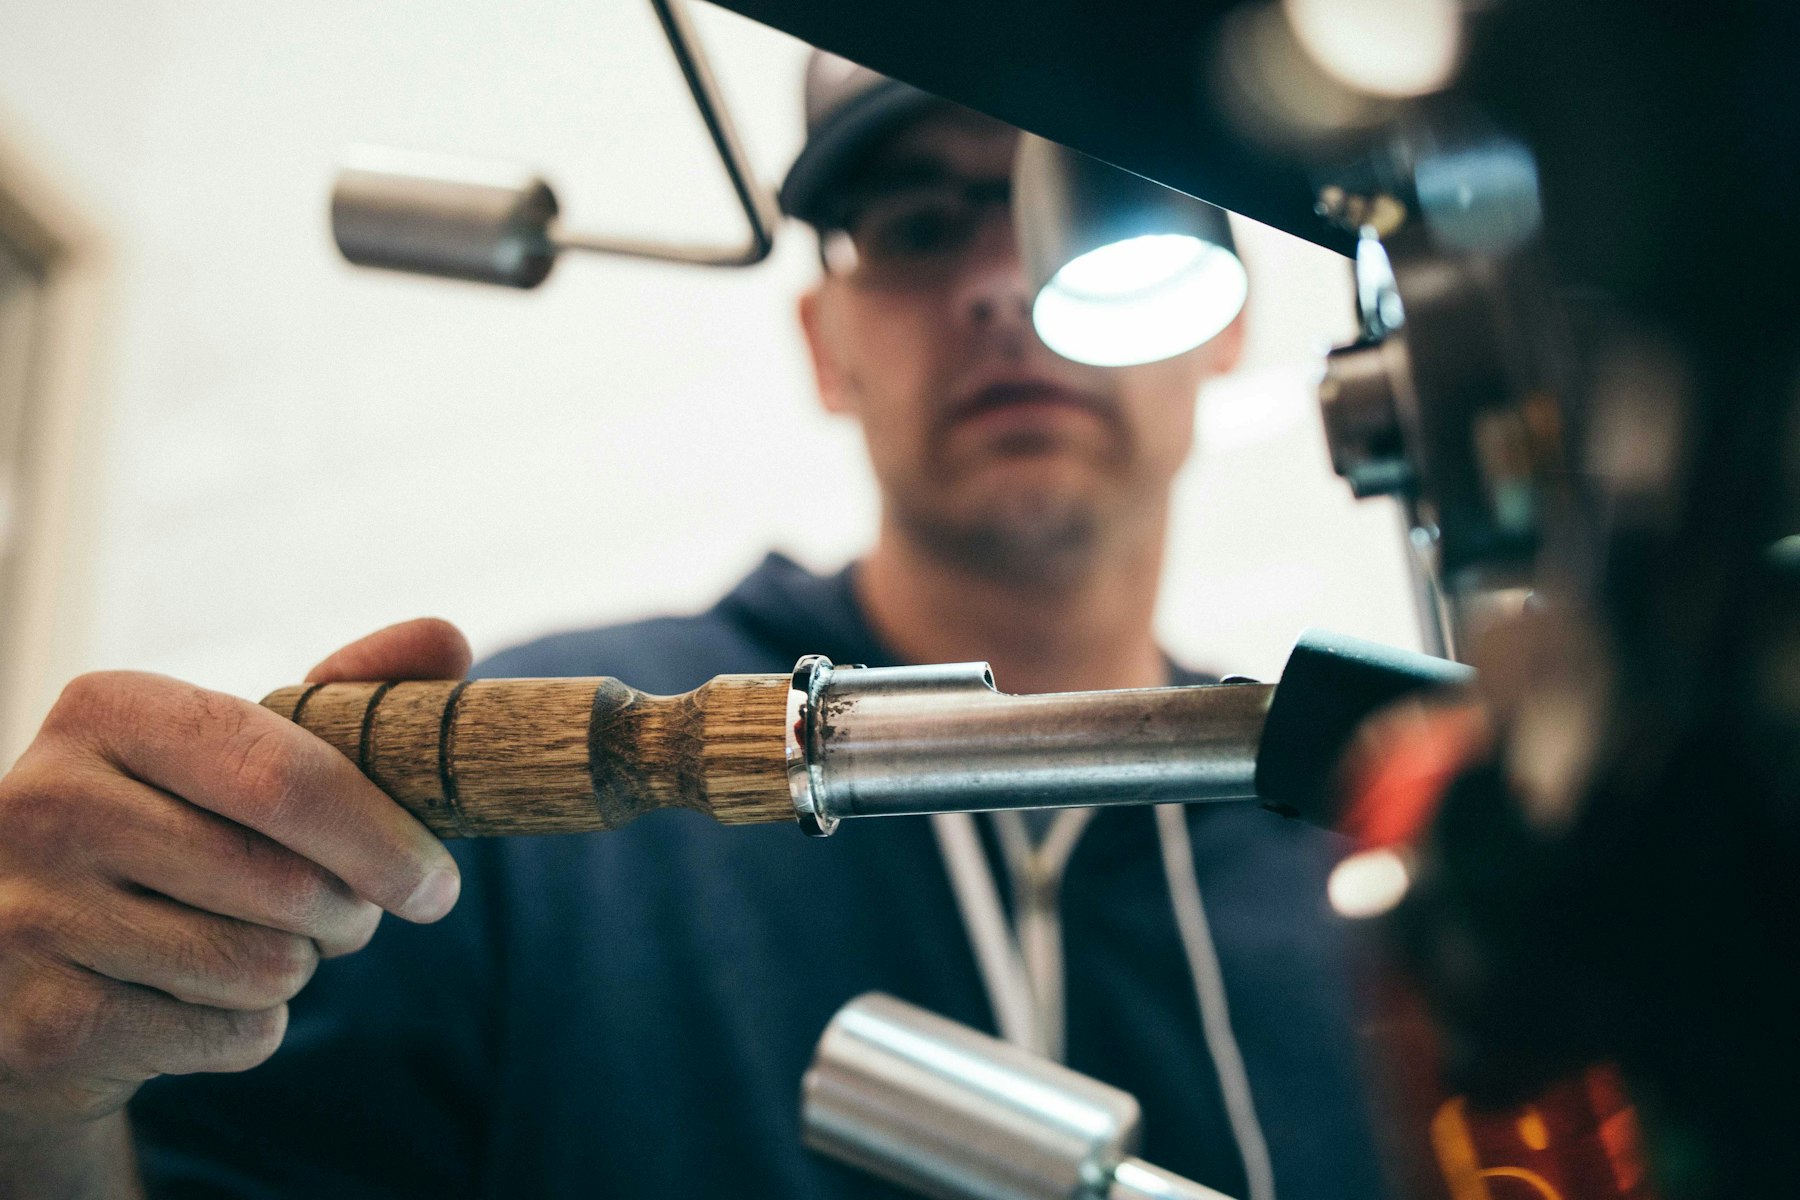
Our family has been in weaving for 22 years with five powerlooms. The VFC Rise desk helped us structure the file clearly — we added one more loom and kept the unit running without starving working capital.
Kannan
Powerloom weaving · KR Thoppu, Salem
Product
Machinery loan
Impact
Added a powerloom
Blog
What MSME means, Udyam on the official portal, and how business loans are mapped — not sanctioned — by this desk.
MSME Knowledge
MSME is India’s official grouping for micro, small and medium enterprises. The Udyam label starts lender and scheme conversations — it is not a loan.
Open page →
MSME Knowledge
Udyam is completed only on udyamregistration.gov.in. Aadhaar, PAN and GST if you have it. VFC Rise cannot register you.
Open page →
MSME Knowledge
Udyam gives lenders a government identity and can open scheme doors. It does not fix a subsidy, rate or sanction.
Open page →
MSME Knowledge
Three Udyam bands, one composite of investment and turnover. Confirm notified limits on the portal. Lenders still underwrite cash flow.
Open page →
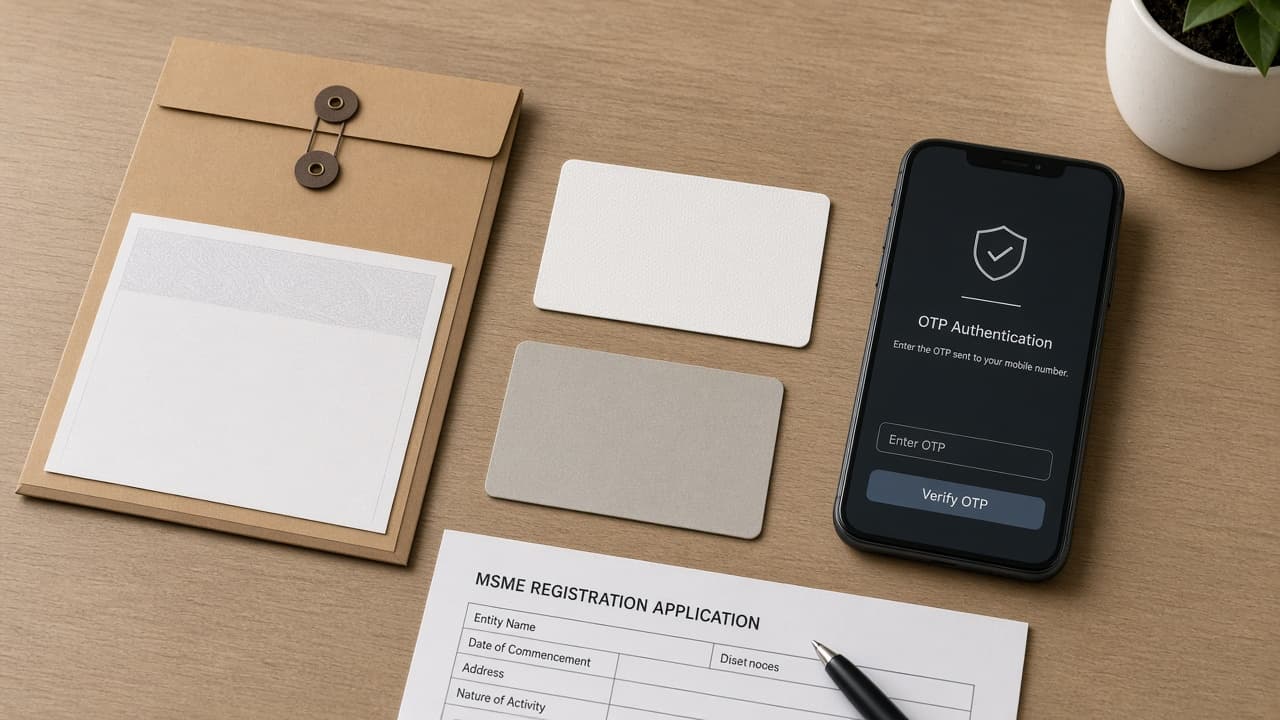
MSME Knowledge
Udyam typically needs Aadhaar, PAN, mobile, GSTIN if you have it, and bank details. The live official form is the source of truth.
Open page →
MSME Knowledge
Status is on udyamregistration.gov.in. This desk cannot see the government queue or move your application.
Open page →
EMI calculator
Adjust amount, rate and tenure to estimate monthly EMI for term-style MSME products — business loan, machinery, LAP and shop loan. Cash credit and overdraft are interest-on-usage, not fixed EMI.
Input mode
Fifteen Lakhs
Monthly EMI
₹ 33,367/month
5 Yrs · 12% p.a. · 60 EMIs
Principal
75%
of total
Principal
₹ 15,00,000
Interest
₹ 5,02,000
Total Payable
₹ 20,02,000
Indicative figures only · Subject to credit assessment · Lender rates apply · DSA desk
Eligibility
Four facts. A likely product — not a yes. Open the service page for documents, or send an enquiry.
Full eligibility notes →This website is an MSME finance desk. Sanction and disbursal, if they happen, are by the concerned bank, NBFC or HFC under their policy. We do not promise a loan.
Popular asks include GST overdraft, unsecured business loan, working capital / CC, LAP, CGTMSE-style, gold loan, PMEGP, Stand-Up India, women-led MSME credit, machinery, invoice lines, CV, shop loan and takeover. All sit under All services.
It is strongly preferred for MSME products and required for many schemes. We still need GST/banking/ITR as applicable.
Some lenders accept a weak year if the trend and banking are otherwise sound. It is a credit call, not a marketing yes.
Enquiry
Write “stock for Diwali”, “CNC quotation” or “shop registry”. Phone 9810929378. No guaranteed sanction, rate or timeline.
VFC Rise is a private limited company working as an MSME finance desk. We do not lend our own money. Sanction, rate, fee and disbursal, if any, are decided by the concerned bank, NBFC or HFC. This website is an information request only.
Quick apply without login, or sign in to upload KYC and track. Working capital, GST OD and LAP — VFC Rise maps the file; the bank sanctions.